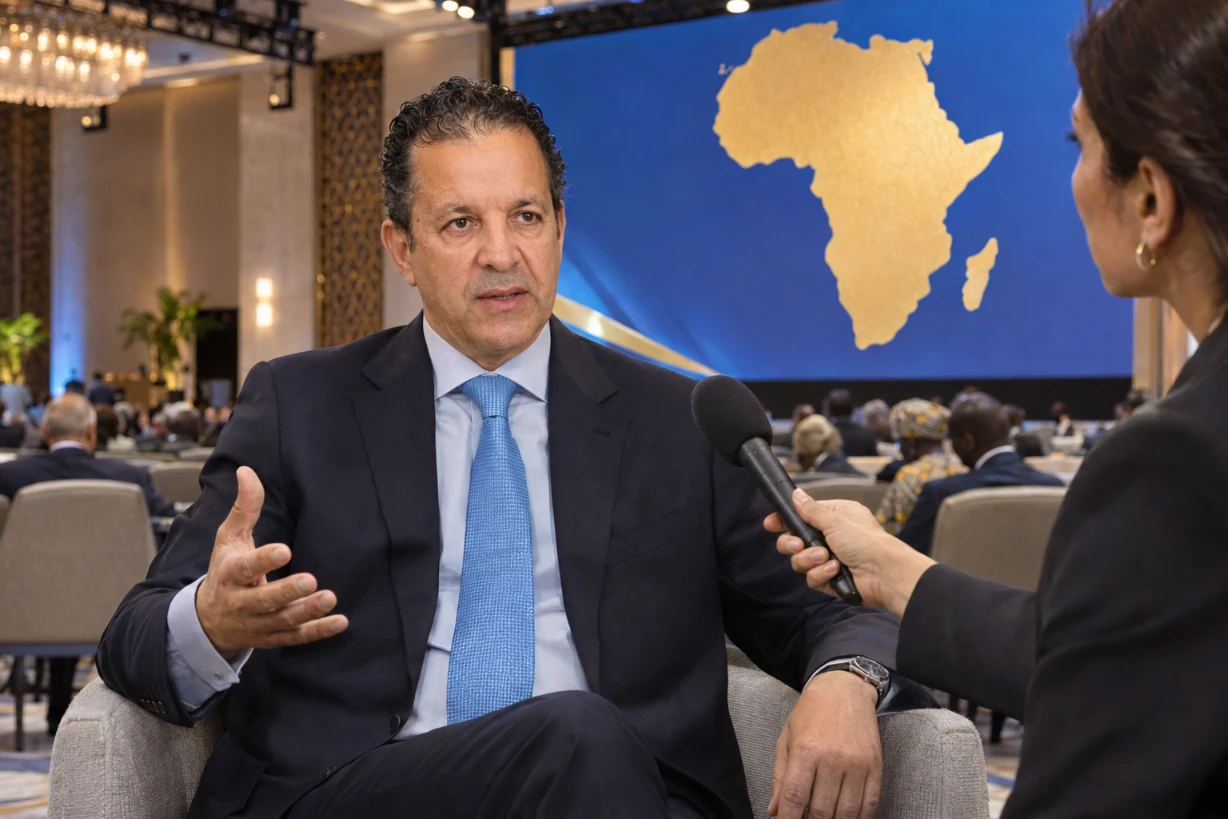
Africa, AfCFTA free trade area according to Nabil Frik: this international expert in finance and foreign trade financing in Africa and the Middle East, formerly Managing Director at British Arab Commercial Bank in London from 2013 to 2025, answers eleven questions. The interview looks at what the African Continental Free Trade Area can change for businesses, the role of African banks, payments, local currencies, currency risk cover, investment, the place of Algeria and the future of the CFA franc. Each answer is given in the first person, drawing on his career in international banking and trade finance.
Who is Nabil Frik?
Today we welcome Nabil Frik, an international expert in finance and foreign trade financing in Africa and the Middle East, whose career links London and Frankfurt.
With more than twenty-five years of experience in international banking, he served, from May 2013 to October 2025, as Managing Director and Head of Financial Institutions for Africa, the Middle East and Asia at British Arab Commercial Bank in London. There he oversaw a portfolio of more than one billion dollars covering more than thirty countries.
His career also includes responsibilities at QNB, Bank of Beirut, Europe Arab Bank, ING Barings and Siemens Financial Services. His expertise covers, in particular, documentary credits, bank guarantees, bank-to-bank relations and the financing of international trade.
With him, we will look at what the African Continental Free Trade Area (AfCFTA) can concretely change for businesses, banks and populations, as well as the opportunities it opens up for Algeria.
1. What changes can the African Continental Free Trade Area (AfCFTA) bring to the economies of African countries and to their trade?
Nabil Frik: AfCFTA can enable African companies to produce for a much larger market, find more suppliers on the continent and build lasting commercial relationships beyond their national borders. We are talking about an economic area of roughly 1.5 billion people, according to work presented by the World Bank in August 2026. The challenge is to make this market genuinely accessible to businesses.
Trade is already growing. According to Afreximbank's African Trade Report 2026, intra-African trade in goods reached about 213.8 billion dollars in 2025, an increase of 5.5% compared with 2024 in the report's revised series. This growth remains influenced by several factors, including prices, economic conditions and existing regional agreements; it therefore cannot, on its own, measure the specific effect of AfCFTA.
The first expected change concerns the size of outlets. A company that can sell in several countries can better amortize its equipment, increase its volumes and invest in quality. This can make viable industrial activities that would be difficult to develop in a single national market.
The second change concerns the processing of raw materials. Take an illustrative example: an agricultural product can be grown in one country, processed in another, packaged in a third and distributed across an entire region. Each stage can create income and jobs on the continent. For this, rules of origin must be understandable and border crossings sufficiently predictable.
The third change affects services. Carriers, banks, insurers, digital companies and engineering firms support every commercial operation. In its 2026 report, the World Bank estimates that deep liberalization of several services could increase trade in services within the area by about 60 to 64% by 2035. This is a conditional projection.
In my view, real progress will be measured by the ability of African companies to produce more together, to retain more added value and to meet the needs of their own markets.
2. What conditions must be met for this trade opening to contribute to job creation and to the industrial transformation of Africa?
Nabil Frik: Companies must be given the means to respond to the opening of markets. A customs preference becomes useful when the producer has electricity, financing, qualified staff and a reliable transport solution.
The first condition is therefore a competitive production base. I would give priority to a regular power supply, equipment maintenance and technical training. A factory that cannot meet its deadlines quickly loses its customers' trust, even when its product benefits from a tariff advantage.
The second condition concerns procedures. In its report presented in August 2026, the World Bank estimates that about 60% of the trade costs studied stem from constraints internal to countries or from unilateral measures. This shows the importance of national reforms: customs, logistics, standards and the functioning of public services. This percentage does not mean that all these costs could be eliminated immediately.
In particular, I would propose simplifying formalities for small businesses, developing risk-based controls and facilitating the recognition of certifications between countries. A manufacturer should be able to know, before shipping, the documents required and the standards applicable to its product.
The third condition is financial. Machines must be financed, but so must purchases of raw materials, inventories and payment terms. A company may have a promising order book and lack the cash to produce. Support must cover this entire cycle.
Finally, workers and companies must be prepared for increased competition. I recommend pairing trade opening with vocational training, apprenticeships, support for local suppliers and transition schemes for weakened activities.
To give an order of magnitude of the potential, a model published in 2022 by the World Bank and the AfCFTA Secretariat estimated that deep integration could create nearly 18 million additional jobs by 2035. This figure describes a success scenario; it does not represent jobs already created.
I would therefore track concrete indicators: lasting jobs, productivity, the number of SMEs that have become industrial suppliers and the growth of processed exports.
3. Are African banks sufficiently prepared to finance the growth of trade between the countries of the continent, particularly for the benefit of small and medium-sized enterprises?
Nabil Frik: Preparation is uneven. The continent has banking skills and networks capable of supporting trade, but the supply of financing still needs to expand considerably to meet the needs of SMEs.
The most recent data published by the African Development Bank are revealing. Its report presented in May 2026 estimates the African trade finance gap at between 74 and 92 billion dollars in 2024. This is an estimate of unmet financing requests.
For SMEs, the same survey shows an average rejection rate of about 35% in 2024 among the banks surveyed. This result indicates that a significant share of companies seeking trade financing do not obtain the response they need.
My approach would be to organize financing around the actual transaction: who is buying, what product is delivered, at what price, within what time frame and with what payment security? A verifiable order, a solid buyer and a properly documented receivable must carry weight in the analysis, alongside the company's financial situation.
Products must also be adapted. An exporting SME may need an advance to produce, post-shipment financing, a guarantee or a factoring solution, that is, financing based on its invoices. The product must match the cash-flow need and the duration of the transaction.
Risk sharing is another essential area. Commercial banks should further develop their partnerships with African development finance institutions and credit insurers. The AfDB already uses guarantee and risk-participation mechanisms to support transactions initiated by African banks.
On the SME side, improving accounting, sales traceability and commercial documentation would make access to credit easier. Banks can support this preparation instead of waiting only for a perfect file.
The operational objective is simple: when a company obtains a credible export order, it must be able to finance, in succession, its production, its delivery and its customer's payment term.
4. How can payments between African companies be made easier, and the costs and delays of cross-border financial transactions reduced?
Nabil Frik: We must work simultaneously on payment infrastructure, the availability of funds and the simplicity of the service offered to businesses.
The Pan-African Payment and Settlement System, PAPSS, represents an important advance. In its 2026 communication, the operator announces a network covering more than thirty countries, linking 24 national and regional central banks and more than 200 commercial banks and payment providers. These figures describe the extension of the network; they do not mean that every company already has all the services available through its usual bank.
PAPSS's technical documentation announces the processing of eligible payments within 120 seconds, with payment and receipt in local currencies. This capability must be distinguished from the total time an operation can take when documents remain to be provided or checks remain to be carried out with the participating institutions.
To accelerate real-world use, I recommend starting with clearly identified trade corridors. We should choose relationships between countries where companies already trade, connect the banks concerned and resolve the practical difficulties encountered by the first users.
Price transparency is also essential. Before confirming a payment, a company must know the amount debited, the fees, the exchange rate and the sum received by its supplier. A very low displayed commission can lose its appeal if the exchange margin is high.
These services must then be integrated into the banking interfaces used every day. The head of an SME should not have to learn several different procedures for each destination.
Finally, I would strengthen coordination between banks to avoid asking for the same documents several times, while maintaining identity, compliance and anti-fraud controls. The quality of data and invoices plays a practical role here.
I would measure success by the full cost of a payment, its actual execution time and the frequency of transactions completed without manual intervention. These are the results that change the daily life of businesses.
5. What role can local currencies play in African trade to reduce dependence on the dollar and the euro?
Nabil Frik: Local currencies can facilitate trade by reducing certain conversions and by allowing companies to make better use of the revenue they earn in their own markets.
Take an illustrative example: on an operational corridor, a buyer pays in its own currency and its supplier receives in theirs. The company can thus make its payment without first having to buy dollars or euros itself. This is notably how the system works for PAPSS users.
However, the entire settlement chain must be examined. PAPSS's documentation provides for daily netting of positions, followed by settlement of balances in hard currency with Afreximbank. Gross foreign-currency needs can therefore be reduced, while some needs remain at the level of final settlement.
The potential also depends on the balance of trade. When companies buy and sell in both directions, part of the payments can offset each other. When a country durably imports much more than it exports on a corridor, the balance must still be financed. A payment arrangement does not automatically correct this economic imbalance.
To develop the use of African currencies, I would favor three conditions: transparent exchange rates, sufficient liquidity and predictable rules for conversion and transfer. Companies must know in which currency they will be paid and what they will then be able to do with their revenue.
We must also better coordinate the currency of revenue with that of financing. A company that sells mainly in its local market should be able to consider financing in that same currency, when its cost and availability allow.
I therefore see the use of local currencies as a practical instrument for reducing commercial frictions. Its development must accompany the growth of trade, the improvement of foreign exchange markets and confidence in financial institutions.
6. How can businesses be protected against the risks linked to exchange-rate fluctuations and to difficulties in converting African currencies?
Nabil Frik: I would begin by distinguishing three risks, because they require different responses: exchange-rate variation, the customer's payment default and the impossibility of converting or transferring funds.
Currency risk arises when a company receives revenue in one currency and bears costs or repays debt in another. My first reflex would be to look for a natural hedge: aligning, as far as possible, the currency of revenue with that of expenses and financing.
When that is not enough, forwards or swaps can be considered, depending on the markets and the applicable regulations. They must be assessed according to their cost, their duration and the obligations they create. Specialized players such as TCX offer this type of hedging on emerging-market currencies, but access and terms depend on the transactions and counterparties.
Non-payment risk requires an analysis of the buyer and of the contract. Depending on the transaction, I would recommend considering a down payment, a documentary credit that is possibly confirmed, a suitable guarantee or credit insurance. The solution must be negotiated before delivery, when the parties can still adjust the commercial terms.
Conversion or transfer risk is different: the customer may have paid, but the funds may remain difficult to convert or transfer. For certain eligible investments and financings, political risk guarantees can provide protection. MIGA, for example, offers coverage against certain public restrictions on conversion or transfer; it specifies that mere currency depreciation is not covered.
I also recommend stress-testing the contract before signing it: what happens to the margin if payment is delayed, if the currency falls or if the cost of conversion rises? These simulations make it possible to adjust the price, the payment dates and the payment security.
Finally, bank risk must be examined. The choice of the institution that receives the funds, issues a guarantee or confirms a documentary credit is part of the company's protection.
Hedging must be built into the commercial structure from the outset. It becomes much harder to arrange when the goods have already been delivered and the problem has appeared.
7. Can AfCFTA attract more international investment while encouraging Africans to invest on their own continent?
Nabil Frik: Yes, because an accessible regional market can improve the profitability of an industrial investment. An investor considering a factory looks at the volumes they will be able to sell, the quality of infrastructure, the applicable rules and their ability to recover the returns on their investment.
AfCFTA can widen outlets and make it possible to distribute certain activities among several countries. I am thinking in particular of projects in which production, processing, logistics and distribution are organized on a regional scale.
The recent figures nevertheless call for a careful reading. According to UNCTAD, foreign direct investment received by Africa reached about 70 billion dollars in 2025, compared with 94 billion in 2024 in the revised series. The year 2024 had been strongly influenced by a few exceptional transactions. The 2025 level remains the third highest since 1990.
I would therefore look at the quality of investments as much as their amount: capacity actually brought into service, jobs created, training, purchases from African suppliers and exports generated. We must also distinguish project announcements from capital actually invested.
To encourage African investors, I recommend strengthening the predictability of rules, the protection of contracts and dispute-settlement mechanisms. An African company investing in a neighboring country must be able to assess its risk with the same rigor as an international investor.
Regional joint ventures can play a useful role. They combine knowledge of the local market, industrial skills and financing from several partners. African development institutions can help prepare projects and share certain risks.
Long-term savings, notably those of insurers and pension funds, could also take part in investments compatible with their obligations of security, return and liquidity. Projects suited to this type of savings must be built, and prudential constraints must be respected.
The credibility of integration will be strengthened when African investors themselves can develop, finance and operate regional projects under predictable conditions.
8. What role can Algeria play in this economic integration, and which sectors could support its non-hydrocarbon exports?
Nabil Frik: Algeria can strengthen its industrial, financial and logistical role by developing sustained commercial relations with its African partners. I would favor an approach based on market needs: identifying the products in demand, understanding local standards and organizing a lasting commercial presence.
The framework already exists. The General Directorate of Customs indicates that Algeria's implementation of AfCFTA began on 1 November 2024. Access to preferences remains tied to the products concerned, the rules of origin and the concessions applicable in partner countries.
As for results, the Minister of Foreign Trade indicated on 5 November 2026 that Algerian non-hydrocarbon exports had reached 5.16 billion dollars in 2025, up by about 972 million dollars compared with 2024. This figure provides a starting point for assessing the progress made and the efforts still needed.
I would distinguish several areas of development. The first concerns construction materials, steel products, fertilizers and certain chemical production. For these activities, I would recommend working particularly on the delivered cost to the customer, consistent quality and storage or distribution capacity at destination. An attractive ex-factory price is not enough to determine final competitiveness.
The second area concerns agri-food, medicines and medical devices. These markets require particular attention to certifications, authorizations and distribution channels. In the date sector, exports reached about 75 million dollars in the first half of 2026, according to the figures presented by the Minister. This half-year figure must be compared with equivalent periods in order to assess growth precisely.
The third area concerns engineering, maintenance and training services, and digital services. I would like their development to be fully integrated into the export strategy, with suitable solutions for contracts, payments and banking support.
Finally, the nature of diversification must be monitored. Some production classed as non-hydrocarbon remains tied to energy inputs. I therefore recommend also measuring the technological content, the skills mobilized and the added value created.
A lasting presence requires local partners, after-sales service and the ability to renew orders. It is this continuity that turns a first sale into a solid commercial position.
9. How can Algerian banks strengthen their support for national companies in African markets and develop local financial partnerships?
Nabil Frik: Algerian banks must be involved in export projects from the preparation of the contracts. This allows them to examine the buyer, the partner bank, the delivery schedule and the financing needs before the company makes commitments.
There are already points of support. Algerian Bank of Senegal appears on the list of authorized institutions published by the WAEMU banking regulator, updated in June 2026. In Mauritania, the Central Bank confirms the start of Algerian Union Bank's activity in 2023. These presences can facilitate the development of local services and relationships.
I recommend first setting up teams specialized by market or by sector. They must be able to understand the commercial contract, assess the buyer's risk and engage effectively with the banks of the destination country.
Next, continuous financial support must be offered: financing of raw materials, production, shipment, then the payment term. The company should be able to present its transaction to a single contact capable of coordinating these different stages.
Local partnerships should also serve to better understand customers and commercial practices. A partner bank can help verify a buyer, organize collections or study financing suited to its situation. These cooperations must rest on precise agreements and a clear division of responsibilities.
In parallel, I would develop risk sharing with African development institutions and credit insurers, depending on the eligibility of transactions. This can allow banks to extend their capacity to provide support while maintaining analytical discipline.
Coordination with companies must also cover documents. A discrepancy between the contract, the invoice, the transport document and the bank conditions can complicate settlement. Documentary preparation therefore deserves as much attention as price negotiation.
Finally, I would measure the performance of these schemes by their results: decision time, number of SMEs supported, volume of transactions actually financed, cost of the service and quality of repayment.
A banking presence becomes particularly useful when the exporter can use it to secure an order, obtain a quick answer and receive payment under the agreed conditions.
10. What priorities should Algeria set in logistics, foreign-exchange regulation and economic cooperation in order to take full advantage of AfCFTA?
Nabil Frik: I would focus action on three complementary workstreams, with measurable objectives and regular coordination among administrations, banks, logistics providers and companies.
The first workstream is logistical reliability. Regular services, groupage solutions for SMEs, predictable customs procedures and storage or distribution services at destination must be organized. An exporter must be able to announce a credible lead time and calculate the total cost of their delivery.
We must be precise about the progress of projects. On 5 November 2026, the Minister was still announcing the handover of the Tindouf free zone before the end of the year. In addition, an official Mauritanian statement of October 2026 mentioned the continuation of work on the Tindouf–Zouérate road. These prospects must therefore be distinguished from services that are already fully operational.
I would propose tracking, for each priority corridor, border crossing times, departure frequency, transport cost and the difficulties encountered by companies. These indicators would make it possible to correct bottlenecks quickly.
The second workstream concerns the predictable application of foreign-exchange regulation. An important change occurred in 2026: Regulation No. 26-02 of 23 July, published on 12 August, sets a maximum repatriation period of 120 days for non-hydrocarbon export proceeds, counted from the shipment of the goods or the performance of the services. A period granted to the customer of more than 120 days, up to 180 days, requires export credit insurance taken out beforehand with the authorized national body. The text also requires repatriation as soon as the customer pays.
This makes it essential to prepare financing and insurance before signing. I recommend better aligning the commercial calendar, regulatory obligations and banking solutions, and making procedures clearer for SMEs.
Companies must also be able to know precisely what options exist for using their foreign-currency revenue, the supporting documents required and the conditions applicable to their commercial expenses abroad. Administrative predictability must accompany repatriation discipline.
The third workstream is economic cooperation based on concrete operations. I would favor programs combining recognition of standards, transit facilitation, banking partnerships, commercial information and dispute settlement. Reciprocal relations must also be encouraged: purchases, sales, co-production and investment with African partners.
Algeria would benefit from first concentrating its efforts on well-identified product-market pairs, then extending the schemes on the basis of the results obtained.
For me, success will be tangible when an Algerian SME can know, before accepting an African order, its delivery cost, its financing need, its collection period and the risks that remain its own, and then repeat that operation regularly and profitably.
11. What future for the CFA franc in Africa? Do its links with France constitute a dependence and an obstacle to the creation of a single African currency?
Nabil Frik: The CFA franc raises a legitimate question of monetary sovereignty. Its history is tied to colonization: it was created in 1945 under the name 'franc of the French Colonies of Africa'. But to assess its future, we must examine precisely how it works today, the reforms already carried out and the economic consequences of the different options.
My approach consists in evaluating a monetary system against several criteria: countries' ability to decide their economic policy, price stability, business financing, export competitiveness and the protection of savings.
How does the CFA franc work? We must first distinguish two CFA francs, issued by two different central banks. In West Africa, eight WAEMU countries use the CFA franc with code XOF, issued by the BCEAO in Dakar. In Central Africa, six CEMAC countries use the CFA franc with code XAF, issued by the BEAC in Yaoundé. The two currencies share the fixed parity of 1 euro for 655.957 CFA francs, but they remain distinct.
The first mechanism is the fixed peg to the euro. The value of the CFA franc does not vary daily against the euro; it does, however, vary against the dollar and other currencies when the euro moves. The second mechanism is the French Treasury's convertibility guarantee, within the framework of the agreements concerned. This guarantee operates at the level of the monetary arrangement and does not exempt companies from foreign-exchange rules and bank controls. The third mechanism is the pooling of reserves and monetary policy within each union.
What dependence on France remains? The situation differs between the zones. In West Africa, the reform launched in 2019 removed the obligation to deposit part of the BCEAO's reserves with the French Treasury and provided for the withdrawal of French representatives from the WAMU's decision-making and management bodies. The parity with the euro and the French guarantee were maintained. In Central Africa, institutional ties remain closer, with French representation in the governance of the BEAC and a conventional threshold of 50% of foreign-exchange reserves to be centralized in the operations account, still mentioned in 2026.
These deposits are central bank assets, recorded in its name and remunerated. The debate therefore does not consist in presenting them as confiscated resources; it concerns their location, their management and the institutional framework of the guarantee. I would thus speak of ties of institutional dependence on the French guarantor and of an economic constraint linked to the euro peg, whose intensity varies by zone.
What are the advantages? The parity makes the cost of purchases and sales denominated in euros predictable, facilitates budget calculation and, if the peg remains credible, helps stabilize certain inflation expectations. A common currency also reduces exchange-rate risk between members of the same union. The pooling of reserves and the convertibility guarantee are safety mechanisms against certain external shocks. However, exchange-rate stability is not enough to ensure the stability of all prices, the financing of the economy or job creation.
What are the disadvantages? The fixed regime limits the room for maneuver of monetary policy, which must preserve the credibility of the parity and sufficient reserves. When the euro appreciates, some products exported outside the euro area may lose competitiveness, even if some imports become cheaper. A single monetary policy must also meet the sometimes divergent needs of several countries. Finally, the colonial history of the system and the ties that remain with France fuel a demand for fully African sovereignty and governance.
Does the CFA prevent a single African currency? It represents an existing framework that would have to be adapted in any broader integration, but it is not the only obstacle. Other African countries often have their own currency and their own policies. The CFA unions offer experience of a common central bank, pooled reserves and regional supervision, from which an African union could draw lessons.
To create a viable single currency, I would retain five conditions: lasting convergence of inflation, public finances and debts; a credible and independent common central bank; financial solidarity among states in the face of asymmetric shocks; banking supervision and crisis-management mechanisms; legal and operational preparation of the transition, notably of deposits, contracts, debts and payments. A rise in the oil price, for example, favors an exporting country and penalizes an importing one: a common monetary policy must be able to coexist with these divergent situations.
What concrete future? We must distinguish the West African ECO from the project of a currency for the whole of Africa. In September 2026, ECOWAS reaffirmed its objective of launching the ECO in 2027, but decisions on governance, the headquarters and the funds were still pending in October: 2027 therefore remains a target and not an established achievement. At the continental level, the African Union is considering a future African Central Bank, a project that requires broader convergence.
For my part, I would favor an evolution decided by African countries, with a public debate on the exchange-rate regime, reserve management and the necessary guarantees. The aim is to strengthen African monetary sovereignty while improving the financing of production and the security of savings. Progress on payments, trade and banking cooperation can begin immediately, before the possible creation of a single currency.
References and Sources
The figures cited in the interview are dated by their publication or their reference year. Projections do not constitute results already achieved.
- World Bank — AfCFTA and integration (28 August 2026)
- Afreximbank — African Trade Report 2026
- World Bank — job and income projections (2022)
- African Development Bank — Trade Finance Report 2026
- PAPSS — how it works and payment
- MIGA — currency inconvertibility and transfer restriction guarantee
- TCX — currency risk hedging
- UNCTAD — African investment 2025
- Algerian Customs — AfCFTA
- APS — Algerian exports and Tindouf (5 November 2026)
- Official Journal of Algeria — foreign-exchange regulation No. 26-02
- WAMU Banking Commission — institutions subject to supervision
- Central Bank of Mauritania — annual report
- BCEAO — history of the CFA franc
- Banque de France — the franc zone
- French Treasury — monetary cooperation
- BCEAO — reform of the CFA franc
- BEAC — Monetary Policy Report, April 2026
- ECOWAS — ECO convergence
- African Union — financial institutions